• Skip to primary navigation
  • Skip to main content
Collective

Collective

A blog to help freelancers with taxes - Collective

What we offer

Business setup Form your business the right way Accounting Expert approved, powered by AI Invoicing Get paid faster, without the busywork Payroll Payroll made simple for S Corps Taxes Stress-free taxes for solopreneurs Business insurance Coverage for your business Health insurance Instant and affordable health coverage Support Human expertise + AI speed
Pricing Customers
About us Partnerships Careers We're hiring! Press
Blog Newsletter Webinars

Free tools

S Corp tax savings calculator Estimated tax & extension calculator Tax calendar S Corp admin cost calculator Freelance rate calculator Bill rate calculator
See all free tools →
Login
Business setup Accounting Invoicing Payroll Taxes Business insurance Health insurance Support
Pricing
Customers
About us Partnerships Careers We're hiring! Press
Blog Newsletter Webinars S Corp tax savings calculator Estimated tax & extension calculator Tax calendar S Corp admin cost calculator Freelance rate calculator Bill rate calculator See all free tools
Login
Resources / Tax Tips · 6 min read

S Corps Become More Valuable With New Social Security Wage Base

The Social Security wage base determines the taxable income for Social Security. Explore the limits and how they impact your S Corp.

Attractive blond man with glasses sitting in cafe, drinking coffee and using digital tablet
T.J. Porter
Written by T.J. Porter
Marissa Achanzar
Updated by Marissa Achanzar
Published May 1, 2023 · Last updated Oct 19, 2026
On this page 5 sections
  1. What Is the Social Security Wage Base?
  2. History of the Social Security Wage Base
  3. How an S Corp Helps You Save Money
  4. Higher Wage Base Means More Savings from S Corps
  5. Final Word

AI Summary

AI-generated from this article. Not tax advice.

  • The Social Security wage base rose from $160,200 in 2023 to $168,600 for 2024, and any income above that limit isn't taxed for Social Security.
  • Self-employed people pay the full 15.3% self-employment tax, made up of 12.4% for OASDI and 2.9% for Medicare, acting as both employer and employee.
  • An S Corp owner splits income into a wage meeting the IRS 'reasonable compensation' standard and distributions of business profit, which aren't subject to the 15.3% FICA tax.
  • On $155,000 of profit with an $80,000 salary and $75,000 distribution, an S Corp saved $10,033 in payroll taxes in 2022 and $11,475 in 2024.

The Social Security wage base plays a role in how much you pay in Social Security taxes and as a result, self employment taxes, which are Social Security taxes and Medicare taxes combined. The Social Security wage base adjusts annually based on the national average wage index. For 2024, the wage base has risen significantly, increasing from $160,200 in 2023 to $168,600.

Quick links
What Is the Social Security Wage Base?
History of the Social Security Wage Base
How an S Corp Helps You Save Money
Social Security Taxes for Sole Proprietors and LLCs
Social Security Taxes for S Corps
Higher Wage Base Means More Savings from S Corps
Final Word

A higher wage base could result in a larger tax bill, making the tax benefits of forming an S Corp more substantial.

What Is the Social Security Wage Base?

First, let’s talk about Social Security taxes, which are officially known as Old-Age, Survivors, and Disability Insurance (OASDI) taxes. These taxes are processed by the Social Security Administration (SSA). Most filers with income pay these taxes, which are 12.4% and split between employers and employees, each paying 6.2%. If you’re self-employed, then you’ll pay the whole 12.4% yourself. 

The Social Security wage base is the maximum amount of wages subject to OASDI taxes. In other words, there’s a limit to the amount of income that’s subject to 12.4% tax. Any income after that limit isn’t taxable for Social Security. 

For example, imagine a taxpayer earns $100,000 per calendar year. They would pay $6,200 in OASDI taxes that tax year, and their small business owner employer would pay the same amount on their behalf. If that person earned $200,000 annually, they’d only pay OASDI taxes on their first $168,600 in earnings. The amount over the limit would not be taxed for Social Security.

As both an employee and employer, self-employed people pay both halves of the tax. This means they pay 12.4% for OASDI taxes in addition to income and other business taxes.

Get help forming an LLC

History of the Social Security Wage Base

The Social Security wage base adjusts regularly based on the national average wage index. It’s a measure of approximate average earnings in the United States. Typically, wages rise every year, leading to a rise in the Social Security wage base.

The first Social Security wage base was established in 1937, where it sat at $3,000 per year. Tax law first increased it in 1951 to $3,600 for tax purposes. Then, it rose every three to six years until 1972, when it started to adjust annually.

The wage base has risen dramatically in recent years. It was $137,700 in 2020 and has increased by over $30,000 in the years since.

How an S Corp Helps You Save Money

Social Security Taxes for Sole Proprietors and LLCs

A business entity that isn’t an S Corp, like a single-member limited liability company (LLC) or sole proprietorship, pays Social Security and Medicare taxes on all of its profit. Medicare taxes don’t have a wage limit so all self-employment income is subject to Medicare taxes.
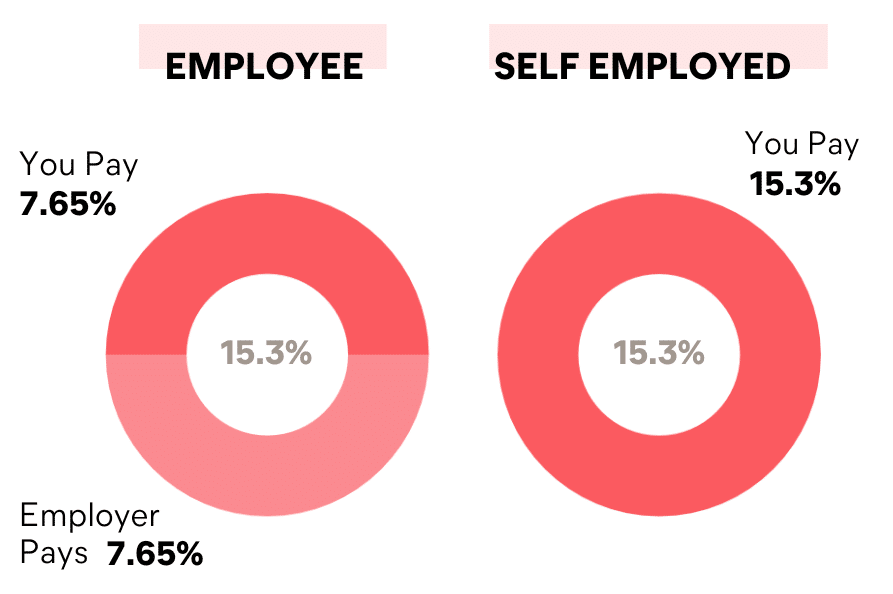
Typically, employers and employees pay 7.65% each in these tax payments. As both employee and employer, sole proprietors and single-member LLC owners pay the full 15.3% in self-employment taxes, which is made up of  12.4% for OASDI and 2.9% in Medicare taxes.

Social Security Taxes for S Corps

S Corps help business owners save money in a few key ways. When it comes to Social Security taxes, the savings come from taking company profits as distributions rather than a wage. Under an S Corp, the owner can split up their income into wages and distributions of business profit. 

S corp shareholder distributions are earnings paid out as dividends. The internal revenue service (IRS) allows S corps to avoid double taxation. The functionality of an S corp is also in its tax rate – S corps don’t pay any income taxes at the corporate level. They’re pass-through entities, so owners report business income and losses on their personal tax returns.

Owners must pay themselves a wage that meets the IRS’s “reasonable compensation” (meaning reasonable salary) standard and wages are subject to Social Security and Medicare taxes (i.e. self-employment tax). 

In a traditional employee-employer relationship, half the Social Security and Medicare tax is paid by the employee and half is paid by the employer. The employer’s portion is considered a cost of running the business. 

This is still true in an S Corp structure where the owner is hired as an employee even though the employee and the employer are the same person (it’s meta, we know). This means the business owner can deduct the employer-paid portion of these taxes (half of the Social Security and Medicare tax paid) as a business expense. That reduces the amount of income they must report from their company on their personal taxes and their income tax liability.

The remaining business profit isn’t automatically subject to Social Security and Medicare taxes- only your owner remuneration is. You can then take any of your additional earnings as a distribution of business profit. Distributions are not employee wages, meaning they aren’t subject to payroll taxes like the federal unemployment tax (FUTA). This lets you avoid the 15.3% Medicare and Social Security tax (FICA). You still have to pay state and federal income taxes, but avoiding 15.3% in taxes is a significant amount of savings.

The only caveat is that your future Social Security benefits are based on your lifetime wages, so taking distributions will slightly reduce your future Social Security income. However, the immediate savings is more than likely to be worth that future decrease in benefits.

Higher Wage Base Means More Savings from S Corps

The ongoing increase in the wage base means that the savings you get from forming an S Corp have only increased. Given that the wage base only goes up, generally, your  savings would get bigger every year.

Imagine you’re self-employed and running a successful small business full-time. Each year, you earn about $155,000 in profit.

In 2022, $147,000 of those earnings would be taxed for Social Security, meaning you’d pay $18,228 in Social Security tax. The full $155,000 would be subject to Medicare taxes, which would cost $4,495 and make your total tax burden $22,273 before income taxes.

In fiscal year 2024, the entire $155,000 you earn is subject to both Social Security and Medicare taxes. In all, you’d pay $23,715. That’s $1,442 in additional tax than what you’d have paid two years ago due to the increase in the wage base.

Table scrolls sideways →

If you formed an S Corp, you might decide to pay yourself a salary of $80,000. That means taking the remaining $75,000 as a distribution.

You’d pay Social Security and Medicare taxes on the $80,000 salary, meaning you’d owe $12,240. You’d only pay income taxes on the $75,000 distribution. That means the S Corporation would save you $10,033 in payroll taxes during 2022 and $11,475 in 2024.

As you can see, generally, your savings from forming an S Corp would increase yearly with the Social Security wage base

Final Word

S Corps let self-employed people and business owners mitigate their tax liability by taking a portion of their earnings as distributions rather than wages. As the Social Security wage base increases, the potential savings from S Corp will only increase, making it a good idea to form one now.

Note: This article is for educational purposes only and refers to tax savings in general. Tax savings with an S Corp is based on your personal circumstance and Collective does not guarantee any tax savings with an S Corp structure. 

Our website contains general information only and this information is not to be taken as legal, tax, or financial advice. You should consult with your attorney and/or tax advisor to get answers to your specific questions.

Get help with your self-employed business

Collective handles the tax and accounting side of your business - so you have more time to focus on your passion. LLC formation, S Corp election. Bookkeeping, monthly financial reporting and an average member tax savings of $10,000*.

Get Started

More on Tax Tips

All Tax Tips posts
Blog

10 Tax Mistakes That Cost Freelance Designers Thousands (and How to Fix Them)

Most tax mistakes freelance designers make aren’t about breaking rules. They come from missing…

Oct 26, 2026 · 10 min read
Tax Tips

Self-Employment Tax Explained: A Guide for Freelancers & Contractors

Self-employment tax explained for freelancers: the 15.3% rate, how to calculate it, a table…

Oct 7, 2026 · 7 min read
Tax Tips

Content Creator Taxes: A Complete Guide for Influencers & Creators

Ad revenue from one platform counts as income. So does a brand deal paid…

Sep 29, 2026 · 8 min read
Tax Tips

W-2 and 1099 Income in the Same Year: How to Handle Your Taxes

Have a W-2 job and 1099 income? Here's how self-employment tax, quarterly payments, and…

Sep 10, 2026 · 4 min read
Tax Tips

7 Best Mileage Tracking Apps for Solopreneurs in 2026

Every client meeting, supply run, and job site visit adds miles to your odometer.…

Aug 19, 2026 · 10 min read
Tax Tips

High-Impact Ways to Reinvest Your Tax Refund Into Your Business

A tax refund feels like found money. It isn’t. It means you overpaid throughout…

Apr 30, 2026 · 4 min read
Blog

Is an S Corp Worth It at $100K in Business Profit?

Earning $100K in business profit? Here's how the S Corp tax savings work, what…

Apr 28, 2026 · 5 min read
Blog

You Missed the Tax Deadline and Didn’t File an Extension. Here’s What to Do.

April 15th came and went. You didn’t file a return, and you didn’t file…

Apr 17, 2026 · 4 min read
Blog

S Corp Disadvantages (and Advantages) Every Solopreneur Should Understand

The S Corp election has a reputation for significant tax savings, and in the…

Apr 9, 2026 · 6 min read
Blog

S Corp Back-Office Options: DIY, Traditional Firm or Integrated Platform

Electing S Corp status is one of the most impactful financial decisions a solopreneur…

Apr 9, 2026 · 5 min read
Blog

Is an S Corp Worth It at $150K in Business Profit?

If you’re a full-time solopreneur making $150,000 in annual profit, you’re in the range…

Apr 8, 2026 · 4 min read
Blog

How to Run Payroll When You’re an S Corp Owner-Employee and Hiring Contractors

Running a business-of-one often involves wearing many hats, but once you elect S Corp…

Feb 12, 2026 · 5 min read
Blog

January 2026: Key Deadlines for Your Self-Employed Business

It’s January 2026 and while the new year often feels like a fresh start,…

Jan 9, 2026 · 3 min read
Blog

IRS Matching Issues: What They Are and How to Avoid Them

When you’re self-employed and managing your business’s taxes, one of the most frustrating complications…

Dec 4, 2025 · 5 min read
Blog

What Solopreneurs Need to Know About the One Big Beautiful Bill Act (OBBBA)

On July 4, 2025, the One Big Beautiful Bill Act (OBBBA) was signed into…

Jul 16, 2025 · 4 min read
Blog

How OnlyFans Creators Handle Self-Employment Taxes

TL;DR: If you’re making money on OnlyFans, you are self-employed—and that means taxes are…

Jun 12, 2025 · 6 min read
Blog

Content Creator Tax Deductions You Might Be Missing

If you’re a content creator, there’s a good chance you’re paying more in taxes…

May 29, 2025 · 5 min read
Blog

Understanding the Differences Between Form 1120-S and Form 1040

What you need to know As tax season approaches, we want to make sure…

Dec 10, 2024 · 2 min read
Blog

How Can a Tax Advisor Benefit My Business

You started your business, and when it comes to taxes, you have no idea…

May 29, 2024 · 9 min read
Blog

1099-K for LLC and S Corp Owners

As a small business owner, you’re responsible for reporting your business activity to the…

Mar 25, 2024 · 5 min read

About the author

T.J. Porter

T.J. Porter

T.J. Porter is a Boston-based freelance writer with nearly a decade of experience, including more than seven years focused on personal finance, covering credit, investing, and banking. His work has appeared in Bankrate, Forbes Advisor, Yahoo Finance, and Credit Karma, among others. He holds a business degree from Northeastern University. See more of his work at TJPorterWriting.com.

All articles by T.J.

Best for S Corp owners

Payroll, books and filings in one membership

LLC Tier $199/mo · S Corp Tier $349/mo

Related

  • 10 Tax Mistakes That Cost Freelance Designers Thousands (and How to Fix Them)
  • Self-Employment Tax Explained: A Guide for Freelancers & Contractors
  • Content Creator Taxes: A Complete Guide for Influencers & Creators

Latest

  • A New Era of Entrepreneurship
  • Collective Raises $100M for Full Stack AI Financial OS Powering the Solopreneur Revolution
  • The Vampire Expenses Draining Your Business

We’re glad you’re here!

First, tell us about your business

Net profit = Total revenue - total expenses

  1. Find total revenue. Add up all money your business earned from sales of goods or services during the year.
  2. Subtract your expenses. Deduct all business costs like supplies, rent, utilities, software, contractor payments, and loan interest.

An estimate is fine, you don't need exact figures.

W2 employees are people on your payroll

You withhold income tax, Social Security, and Medicare from their paychecks, and they get a W-2 form from you at the end of the year.

Don't count yourself (even if you pay yourself a salary) or 1099 contractors and freelancers.

I agree to Collective Terms of Service & Privacy Policy. Additionally, by providing phone number to continue, I agree to receive calls, incl. autodialed or prerecorded sales calls, from Collective.

Collective logo

We are experts in the unique needs and challenges of self-employed people and know that our confidence gives others confidence, too. Reach out to say hello and join our team.

We are experts in the unique needs and challenges of self-employed people and know that our confidence gives others confidence, too. Reach out to say hello and join our team.

Products

  • Business setup
  • Accounting
  • Invoicing
  • Payroll
  • Taxes
  • Business insurance
  • Health insurance
  • Support
  • Late S Corp election

Company

  • Home
  • Pricing
  • About us
  • Careers
  • Contact us
  • Partnerships

Resources

  • Blog
  • Guides
  • Help center
  • Testimonials
  • Press
  • Create with us

Legal/Support

  • FAQ
  • Terms of service
  • Privacy policy
  • Security policy

Compare

  • Compare all
  • Collective vs Lettuce
  • Collective vs LegalZoom
  • Collective vs TurboTax
  • Collective vs ZenBusiness

Collective provides a suite of tools, back-office support, and general information. Our services are not intended as tax, legal, or professional advice.

* Savings estimates reflect the average 2023 federal self-employment (SE) tax savings for Collective members with an S Corp tax election, based on business profits that would've otherwise been subject to SE tax. Actual savings will vary based on individual circumstances.

** Based on data sourced from Shopify blog, QBO Essentials, QBO Live, Gusto, Taxfyle, Intuit "Tax Pro" Research, LegalZoom and JustAnswer.com as of August 2025.

† Individual tax return packages are billed as an annual, one-time add-on fee.

© 2026 Collective Hub, Inc. All rights reserved